7.2% CAGR signals the next wave of AI, EV and Advanced Computing growth
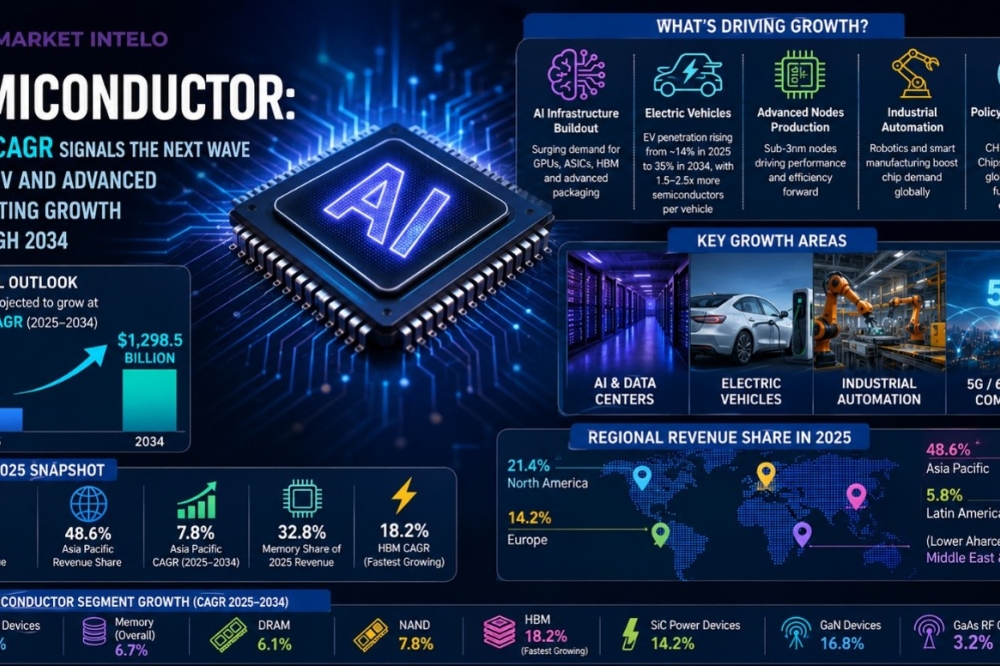
According to Market Intelo, the global semiconductor market is expected to grow from $681.1 billion in 2025 to $1,298.5 billion in 2034, growing at a CAGR of 7.2%. This is being driven by three factors the development of AI infrastructure, automotive electrification, and transition to sub-3 nanometer semiconductor processes.
What Makes this Growth Phase Unique
For decades, semiconductor demand has been moving in a three-to-five-year cycle of shortages and oversupply. What makes this phase unique is that there is structural growth rather than just cyclical growth. AI accelerators, HBM, and silicon carbide (SiC) power devices did not exist five years back and have turned into entire new pools of semiconductor content. Logic devices (7.9% CAGR) and HBM (18.2% CAGR) are growing significantly faster than the rest of the market, whereas categories such as gallium arsenide RF components (3.2% CAGR) are lagging behind.
Latest Developments Affecting the Semiconductor Market
Capex for AI accelerators is now scarce. The capital expenditure of hyperscalers is dictating the future of foundry roadmaps, as revenues from data center accelerators, which include NVIDIA GPUs, alongside custom silicon of hyperscalers such as Google's TPUs and Amazon's Trainium, are forecast to surpass USD 180 billion by 2034.
HBM is the industry's most constrained technology. Growing at CAGR of 18.2%, with a price premium of 18-22% compared to DRAM, HBM is led by SK Hynix (~51% market share). Samsung and Micron are qualifying next generation capacity, but the race is becoming one of advanced packaging.
Leading-edge capacity is increasing on three continents. In Taiwan and Arizona, TSMC is scaling 3nm and below 3nm process technologies; in South Korea, Samsung is ramping 3nm GAA process technologies and researching 1.4nm technology; in Ohio and Arizona, Intel is rebuilding its foundry business based on 18A and 14A process technologies. Capex for advanced nodes exceeded USD 145 billion in 2025.
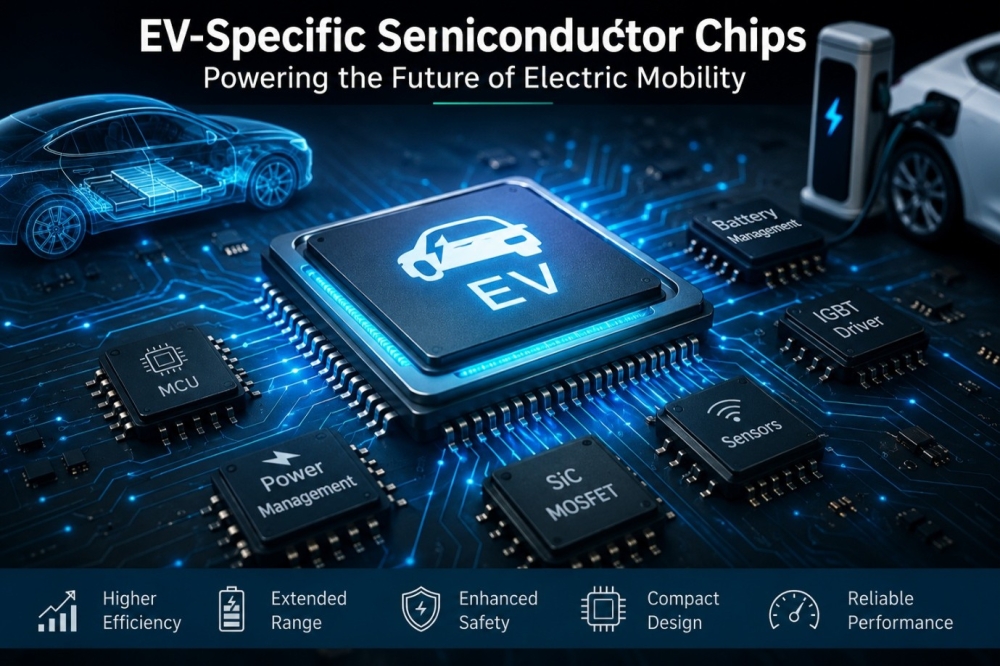
Materials are driving change in power semiconductor technology. Despite representing a small portion of total revenue (4.8% for SiC and 2.1% for GaN in 2025), their growth rates are 14.2% and 16.8%. Eight to twelve SiC MOSFETs are needed per EV powertrain, and GaN is moving from fast chargers to server power and 5G/6G RF infrastructure.
Industrial policy is a permanent input in planning going forward. The CHIPS Act of the United States (USD 52.7 billion), Chips Act of Europe (USD 43 billion), and similar initiatives in South Korea and Japan are no longer one-off stimuli but a continuous variable in capacity plans.
Market Outlook 2025–2034
Asia Pacific is still the main weight, representing 48.6% of revenues in 2025 with an approximate CAGR of 7.8%. The contribution from Taiwan is about 19.2% of global revenues, powered by TSMC’s foundry business, South Korea around 18.1% from Samsung and SK Hynix’s memory and HBM business, and China and Southeast Asia adding 11.3%, driven by Beijing’s efforts for memory and mature-node self-reliance.
North America has 21.4% of value based on design (fabless), EDA tools, and packaging innovation rather than manufacturing capacity; its 6.9% CAGR rate falls below the global average while its CHIPS Act funding of new fabs starts ramping up in Arizona, Texas, and Ohio. Europe has 14.2%, set to grow by 6.1% CAGR rate with strength in analog and power semiconductors and CHIPS Act funding for mature nodes (28nm+); these are for automotive and industrial customers. Latin America (with 5.8% market share) and the Middle East & Africa have lower shares but grow faster (8.1% and 8.9% CAGR).
By type of semiconductor, memory still dominates as the biggest segment (32.8% of 2025 revenues), but logic devices (accounting for 28.1%) grow faster (7.9% CAGR due to GPUs and AI accelerators). Memory types also differ in growth rates – DRAM (6.1% CAGR) and NAND (7.8% CAGR) lag well behind HBM (18.2% CAGR).
Important Growth Drivers
• AI infrastructure buildout – cloud capital expenditure on AI hardware increased 35–40% year-on-year, leading to the increase in demand for GPU, ASIC, HBM, and packaging.
• Electric Vehicles – fastest-growing segment with 9.2% compound annual growth rate, as EV penetration increases from about 14% of new sales in 2025 to 35% in 2034 (~62 million electric vehicles annually) with 1.5–2.5x the number of semiconductors compared to a combustion engine car.
• Further advanced nodes production – continued development of sub-3nm nodes at TSMC, Samsung, and Intel alleviates the supply challenges of 2021–2023.
• 5G/6G deployments – subscription to 5G/6G is expected to be 4.7 billion in 2034, driving ~7.6% CAGR demand for RF and baseband devices.
• Wide-bandgap materials – power conversion efficiency of SiC is 95-98% compared to silicon with 90-92%, contributing to the EV range and fast.
Industry Context: Structural, Not Just Cyclical
The trend toward capital expenditure is another aspect that highlights the above changes. The top 10 semiconductor firms account for 62% of total revenues due to the fixed costs involved in competing at the cutting-edge level and the supply chain security. By itself, TSMC has 54% share of advanced logic fabrication capacity worldwide and is planning growth from USD 76.2 billion of 2025 revenues to an estimated USD 158.4 billion by 2034, when the foundry industry is expected to nearly double despite significantly slower growth in volumes.
Concentration goes beyond foundries as Samsung, SK Hynix, and Micron command 73.4% and 67.4% market shares for DRAM and NAND memory respectively; in the equipment market, Applied Materials has around 40% market share, ASML controls more than 95% of EUV lithography, and Lam Research has nearly 1/3 market share for etch segment. Resilient supply chain strategy needs to consider single points of failure even at the toolmaker level.
Regulatory Developments to Track
National subsidy programs are reshaping where capacity gets built. CHIPS Act funding is catalyzing U.S. fab construction, while the European Chips Act channels investment toward mature-node capacity for automotive and industrial customers rather than leading-edge logic. South Korea's K-Semicon and Japan's JASM partnership add further state-backed expansion, gradually reducing the industry's historical concentration in Taiwan.
Export controls remain a live, moving variable. Restrictions on advanced lithography, process-control tools, and leading-edge AI accelerators bound for China continue to evolve. Companies with exposure to Chinese fab customers must now build regulatory renewal risk directly into revenue forecasting rather than treating export policy as a fixed backdrop.
Geopolitical fragmentation is indeed a realistic threat for the future. The U.S.-China technological restrictions and the European moves towards strategic autonomy will result in splitting the world market and reducing the economies of scale which have made chips cheaper — the reason why dual sourcing is needed despite increased costs.
Adoption Trends Worth Watching
• Custom silicon adoption is picking up speed, with 3-5% of procurement moving towards OEM-customized, foundry-manufactured silicon (Apple, Tesla, Google). This will affect the demand dynamics for merchant semiconductor supplier.
• Chiplets and heterogeneous integration technologies are now coming to market, which will create new business opportunities for packaging and process control specialists.
• There are qualification cycle constraints with HBM, as three players become more and more crucial for launching new AI accelerators.
• SiC and GaN are getting more widespread from automotive into data centers, renewables, and charging technologies.
Opportunities and Risks
The most obvious opportunities include niche areas such as SiC/GaN power conversion, AI accelerators and HBM, automotive sensor fusion, and advanced packaging as well as new greenfield markets in India, Southeast Asia, and Latin America, where smartphone adoption is expected to rise from 54% to 72% by 2034.
The same factors also carry risks. Further scaling at advanced nodes will soon reach physical and economic constraints, demanding R&D that only a few players can afford. Standard memory is subject to cycles, specialty components (rare earths, photoresists, EUV systems) may become bottlenecks, and quantum and optical computing could be a long-term threat to classical semiconductors.
Insights for Decision-Makers
These insights suggest that the growth in the industry in the coming years will be more dependent on the increase in silicon and value per device rather than sheer volume. Original Equipment Manufacturers (OEMs) and systems companies need to view semiconductor purchases — especially AI accelerators, HBM, and automotive power semiconductors — as long-term engagements based on technology roadmaps.
In addition, for chipmakers, foundries, and equipment suppliers, the areas where current capital expenditure would determine their market share in the future are logic devices, HBM, SiC/GaN power semiconductors, and advanced packaging. To policymakers and investors, the interactions between subsidy schemes, export controls, and AI infrastructure build-outs have made this market one of the best real-time indicators of technology policy and its impact on global supply chains.
It is a big opportunity, a market that is anticipated to more than double in size, from USD 681.1 billion to USD 1,298.5 billion, in the next decade.
Reference: https://marketintelo.com/report/semiconductor-market
Author Bio:
Raksha Sharma is an industry research and business insights professional associated with Marketintelo. She focuses on researching emerging industries, market trends, technological developments, and evolving business landscapes. Through data-driven content and industry analysis, Raksha brings practical perspectives on key developments shaping global markets and helps readers understand complex industry trends through clear, accessible insights.